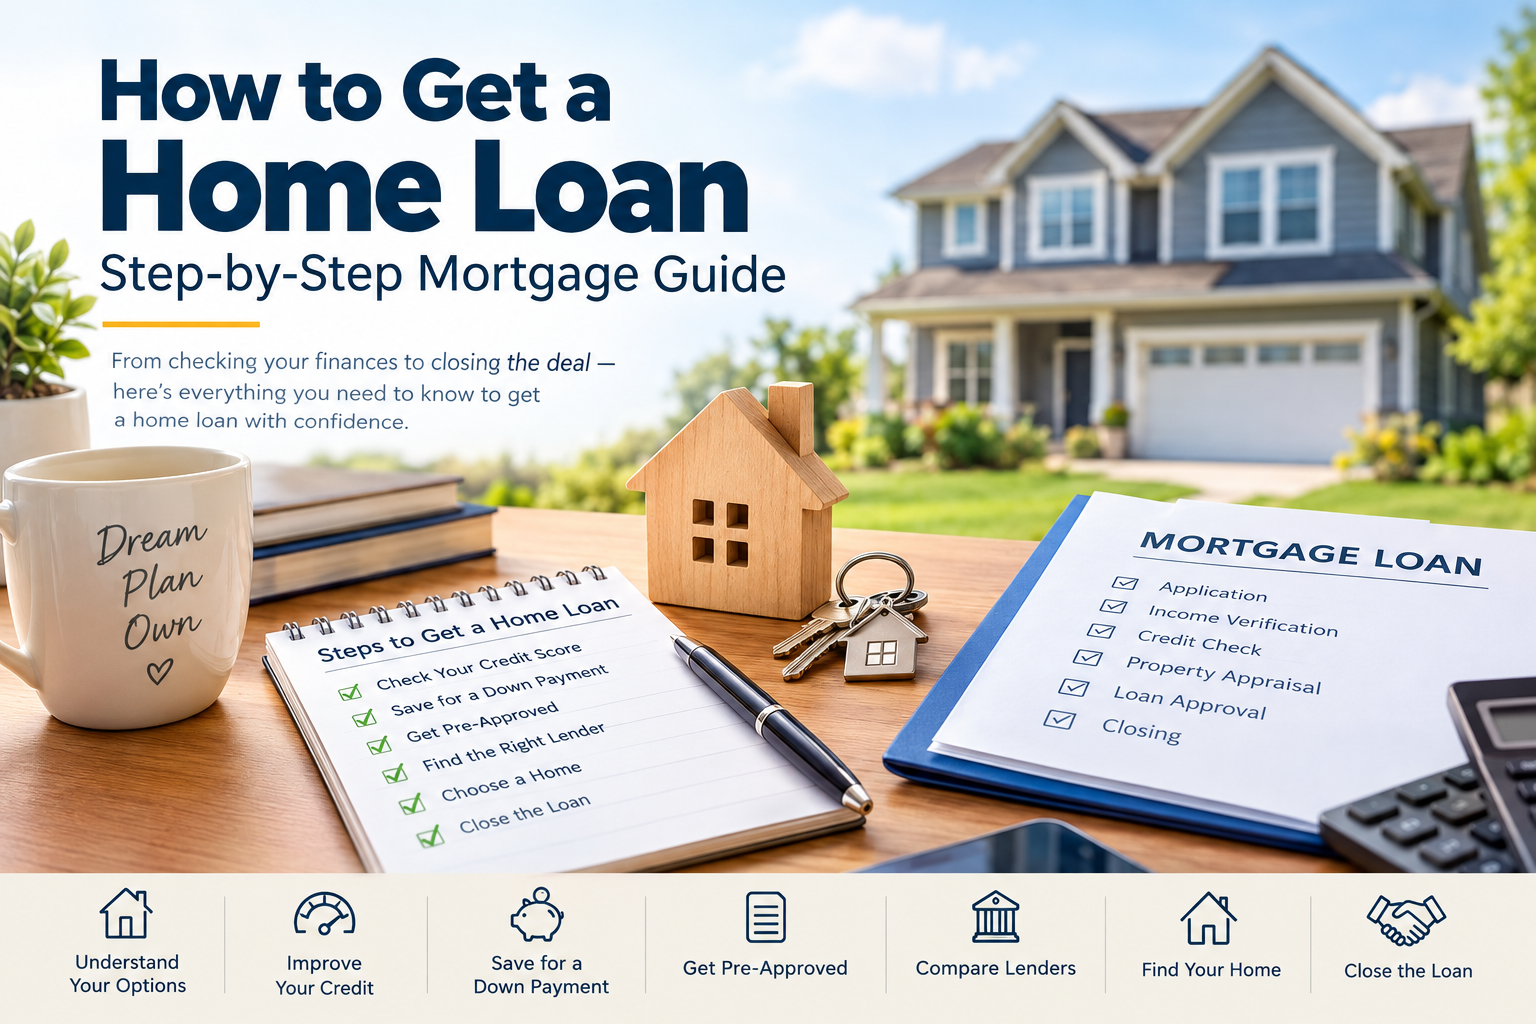
When you purchase a home with a mortgage, homeowners insurance is an important part of the financial picture. Insurance can help protect against covered property losses, while the mortgage protects the lender’s financial interest in the property.
Understanding how homeowners insurance works can help buyers prepare for closing and estimate the ongoing cost of homeownership.
Why Is Homeowners Insurance Important?
Homeowners insurance can provide coverage for certain accidental damage and other risks covered by the policy. The exact protection depends on the policy, exclusions, limits, deductibles, and applicable terms.
Mortgage lenders typically require homeowners insurance as a condition of financing. Homeowners can choose their insurance company and should compare coverage and pricing before closing.
How Does Insurance Affect a Mortgage?
Homeowners insurance is separate from the mortgage itself, but the premium can affect your monthly housing expenses.
Depending on the mortgage arrangement, insurance premiums may be collected through an escrow account along with property taxes.
This means a buyer who focuses only on principal and interest could underestimate the actual monthly housing payment.
Compare More Than the Premium
When comparing homeowners insurance, the cheapest premium is not necessarily the only factor to consider.
Look at coverage limits, deductible, covered risks, exclusions, replacement-cost provisions, personal property coverage, liability coverage, and additional living expense coverage.
What Is a Deductible?
A deductible is the amount you are generally responsible for paying before the insurer pays covered claims, subject to the policy’s terms.
A higher deductible may reduce the premium in some circumstances, while a lower deductible can increase the premium.
Homeowners should consider whether they could comfortably pay the deductible if a covered loss occurred.
Flood Insurance May Be Separate
One important issue for homebuyers is flood coverage.
Standard homeowners insurance typically does not cover flood damage. Homebuyers in areas with flood risk may need separate flood insurance.
What Can Affect Insurance Costs?
Several factors can influence homeowners insurance costs, including location, property size, construction type, roof condition, age of the property, disaster risk, deductible, previous claims, rebuilding cost, and safety features.
Insurance companies use their own underwriting methods, so prices can vary between insurers.
Insurance and Mortgage Closing
Before closing on a home, your lender may ask for proof of insurance that meets its requirements.
It is a good idea to arrange coverage early rather than waiting until the final stage of the purchase.
Your loan officer can explain the lender’s requirements, while your insurance provider can explain what the policy covers.
What Happens If Insurance Is Canceled?
If required homeowners insurance is canceled or lapses, a mortgage lender may take steps to protect its interest in the property. This can involve lender-placed or force-placed insurance.
The terms and consequences depend on the mortgage agreement and applicable law.
Don’t Forget About Maintenance
Insurance is not a substitute for routine home maintenance.
Homeowners are generally responsible for maintaining their property. Insurance coverage depends on the cause of damage and the specific policy.
Regularly checking the roof, plumbing, electrical systems, heating and cooling equipment, and other important components can help identify problems before they become expensive.
Final Thoughts
Homeowners insurance is an important part of the home-buying process. Mortgage borrowers should consider insurance premiums, deductibles, coverage limits, exclusions, and potential additional policies when calculating the true cost of owning a home.
Before purchasing a policy, compare several quotes and carefully read the coverage details.
This article is general educational content and should not be considered insurance, legal, tax, or financial advice.