Buying a car with a limited or damaged credit history can be challenging, but there are financing options available in the marketplace. The key is understanding the cost of borrowing and avoiding a loan that creates an unaffordable monthly obligation.
Credit history is one factor lenders may consider when determining auto loan terms. Borrowers with lower credit scores may receive higher interest rates, which can increase the total cost of a vehicle loan.
What Is a Bad Credit Car Loan?
A bad credit car loan generally refers to auto financing offered to borrowers whose credit profile may not qualify for the most competitive conventional rates.
A lender may consider credit history, credit score, income, existing debt, employment, down payment, loan amount, and vehicle characteristics.
Check Your Credit Before Applying
Before searching for a loan, review your credit information.
Look for incorrect account information, duplicate accounts, incorrect payment history, accounts that do not belong to you, and other reporting errors.
Knowing your credit situation can also help you understand why lenders may offer different terms.
Save for a Down Payment
A down payment reduces the amount you need to borrow.
For example, if you purchase a $20,000 vehicle and provide $4,000 upfront, you need to finance less than if you borrowed the entire amount, before taxes and other applicable costs.
A larger down payment can therefore affect the amount financed, although borrowers should also preserve appropriate emergency savings.
Compare Multiple Lenders
Do not assume that the first financing offer is the only option.
Compare banks, credit unions, online lenders, and dealer financing where appropriate.
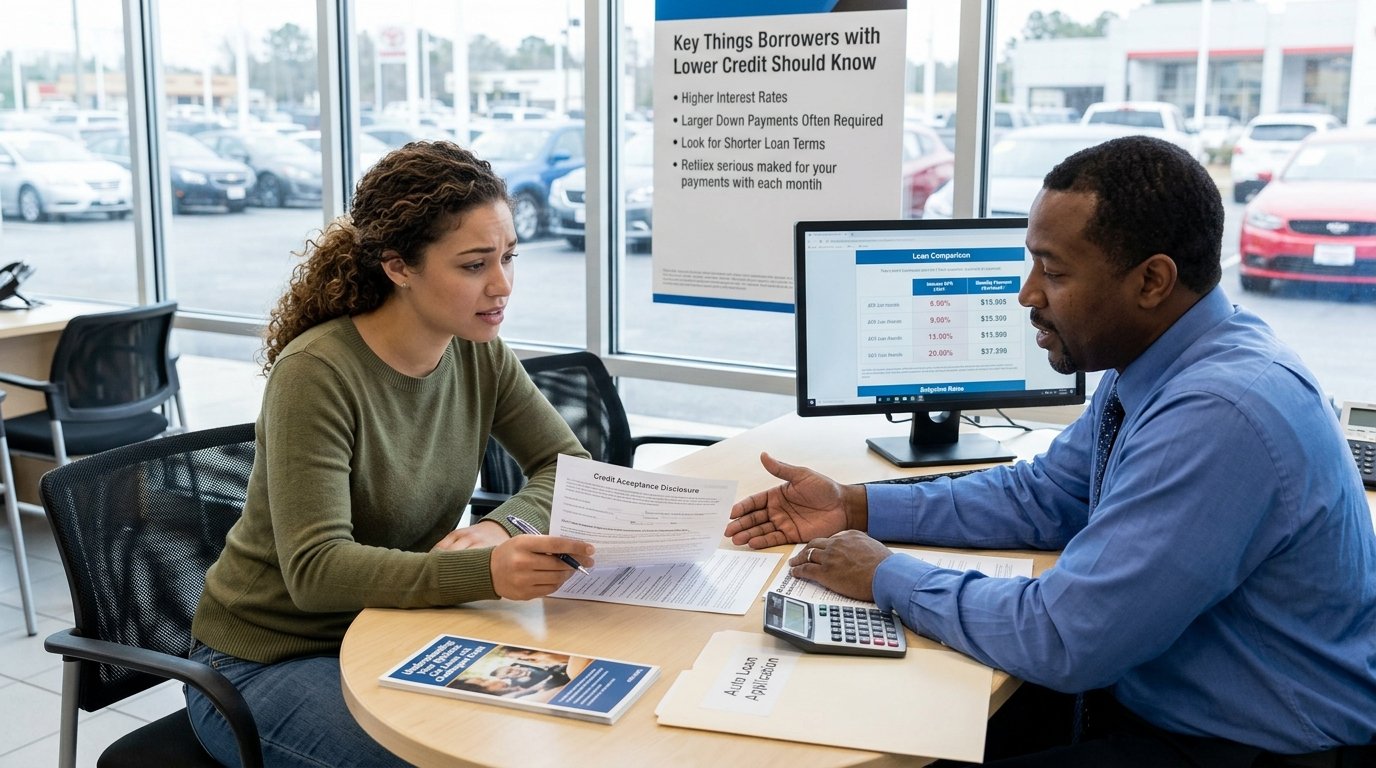
Compare APR, interest rate, loan term, amount financed, monthly payment, total finance charges, and fees.
Be Careful With Long Loan Terms
A long loan term can reduce the required monthly payment.
However, it may also increase the total interest paid over the life of the loan.
This can be particularly important when financing a used vehicle because the borrower may still owe money after the vehicle has experienced significant depreciation.
Consider the Vehicle, Not Just the Loan
The cheapest vehicle to finance is not always the cheapest vehicle to own.
Consider fuel economy, maintenance, repair costs, insurance, vehicle reliability, registration, and expected ownership period.
Watch for Optional Add-Ons
Some dealerships may offer additional products during financing.
Examples include GAP insurance, extended warranties, credit insurance, and service contracts.
These products may have legitimate uses, but consumers should understand the price, coverage, limitations, and cancellation rules.
Beware of Payment-Focused Sales
A dealer may ask what monthly payment you want.
Remember that the same monthly payment can be created by changing the vehicle price, interest rate, down payment, or loan term.
Ask for the full financing information instead of negotiating only around the monthly payment.
Final Thoughts
Bad credit does not mean you should accept the first loan offer you receive. Compare multiple lenders, understand the APR, consider a reasonable down payment, and evaluate the complete cost of owning the vehicle.
Most importantly, choose a loan payment that fits your actual budget rather than stretching your finances simply to purchase a more expensive vehicle.
This article is educational and not personalized financial advice.